Property Valuation for Inheritance in the Netherlands
How to value an inherited home in the Netherlands, separate tax and estate decisions, prepare documents and choose the right valuation date.
TL;DR: define the decision first
An inherited home does not have one universal value for every purpose. Start by writing down what the valuation will support: an inheritance-tax return, a division between heirs, a sale, a buyout or a later financing decision. Then confirm the relevant valuation date and ask which report the person or organisation receiving it will accept. If this is your situation, use the steps below to decide which facts and questions matter for you.
If you are preparing a property valuation, keep local market context such as property valuation in Expat Taxatie, Amsterdam separate from the property-specific evidence and report purpose.
If your question concerns tax or WOZ, keep the tax rule and WOZ value through the official portal as separate parts of the assessment.
For inheritance tax, the Belastingdienst explains how to value an inheritance. A home is usually valued using the WOZ value for the year of death or the following year, with the lower value available in the situations described by the tax authority. If the home was substantially changed before death, market value may apply. A tax value is not automatically the right value for a buyout or a sale.
Use this sequence:
- Name the decision, recipient and valuation date.
- Collect the will, ownership, mortgage, WOZ and property documents.
- Ask a valuer for the exact scope and report format.
- Review the report for facts, assumptions and date.
- Use the result with the notary, tax adviser, lender or other recipient.
Does this situation match your question?
If you are an heir, executor or family member dealing with a home in an estate. It is useful when the family needs a value before deciding whether to sell, keep the property or let one heir buy out the others.
If you are transferring a property as a gift, record property valuation for a gift with the date, parties and tax question.
It also helps when people use the word “value” to mean different things. A tax return, a family agreement and a mortgage application can ask for different evidence. If the purpose is unclear, a quote comparison will not solve the underlying problem.
If you are selling, match property valuation before selling to the sale decision, valuation date and negotiation.
Why an inherited home needs a clear valuation question
An estate can include the property, a mortgage, other debts and rights of use. The Belastingdienst describes the value of an inheritance as assets minus debts. That is a calculation of the estate, not a statement that every heir owns the same share of every asset.
The value can also depend on the date. The home may have changed after the death, the market may have moved and the report recipient may use a different date. A later sale price is evidence of a transaction at a later time, not proof that the earlier value was wrong.
The Belastingdienst’s inheritance guidance explains why holding, selling and buying out other heirs can lead to different decisions.
If you are dividing home equity, keep property valuation during divorce tied to the valuation date and ownership shares.
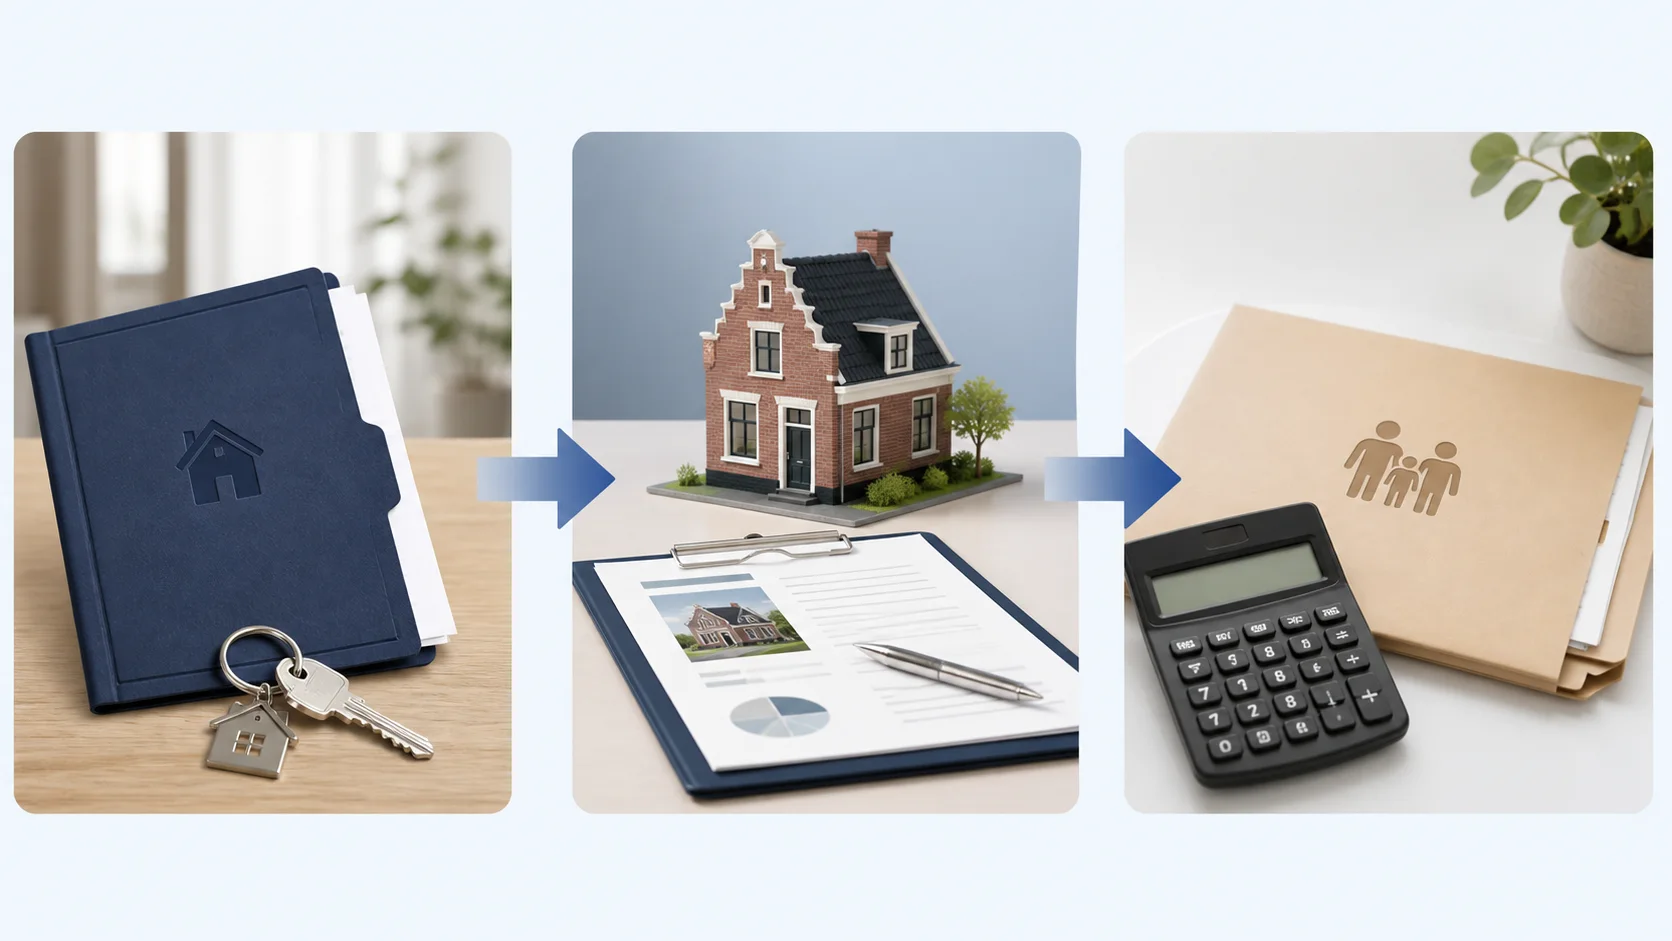
The visual below turns the decision into three stages: establish the estate facts, obtain the right valuation evidence and then use the result for the specific decision.
Before you appoint a valuer, define the right type of property valuation by the purpose and report recipient.
Documents and decisions to assemble
Make one shared file before contacting a valuer. Keep the original documents and note any gaps rather than filling them with estimates.
- Purpose and date
- Write whether the value is for inheritance tax, a buyout, a sale, a division or another defined decision.
Tax value, market value and estate value are not interchangeable
A value for inheritance tax
The tax authority gives a specific route for a home. Its guidance says to use the WOZ value for the year of death or the following year when known, choosing the lower value. If the home was substantially changed before death, the guidance points to market value instead. An annual ground-rent payment can also affect the value used for inheritance tax in the manner described by the authority, including the 17-times rule.
These rules answer a tax question. They do not tell the family what a fair buyout price should be without considering ownership shares, the property’s condition and the agreement between the heirs.
A market valuation for a sale or buyout
A professional valuation can estimate the market value on a stated date. It may examine the property, legal position, comparable sales, condition and restrictions. For a buyout, the report should make clear whether it values the full property and how the parties should apply their agreed shares.
A value for financing or another recipient
If one heir keeps the home and needs a mortgage, the lender can impose its own report and date requirements. A valuation prepared for tax or family division may not meet those rules. Before you appoint a valuer, define the right type of property valuation by the purpose and report recipient.
The inheritance valuation process in six steps
1. Name the decision and date
Write one sentence: “We need the value for [purpose], for [recipient], at [date].” If the date is disputed or unclear, ask the notary or adviser before booking.
2. Map the rights and debts
Confirm who owns the home, who inherits it, whether anyone has a right of use and what mortgage or other debts remain.
3. Collect the evidence
Send the same factual brief to any provider you compare. Include property details, ownership, the relevant WOZ notice, improvements, leasehold, occupancy and the documents that explain the estate.
4. Confirm the assignment
Ask what the report will contain, whether an inspection is needed, which valuation date will be used and how the valuer will handle missing information. A low fee is not useful if it buys the wrong assignment.
5. Check the report
Read the address, ownership description, floor area, rights, condition, comparable evidence, assumptions, valuation date and conclusion. Ask for factual corrections before anyone uses the report in a tax return or agreement.
6. Apply the value with the right adviser
Give the completed report to the person who requested it. A valuer explains the property value; a notary, tax adviser or lender explains what that value means for the legal, tax or financing decision.
Four inheritance situations
One heir keeps the home
The heir may want to live in or sell the home. A tax value may be enough for one filing, while a mortgage or sale needs a different report. Keep those decisions separate.
Several heirs divide the estate
The family needs both the property value and the ownership or inheritance shares. Do not assume that an equal family relationship means equal ownership; verify the legal position.
One heir buys out the others
Use a stated market value and document how the mortgage, costs and ownership shares are applied. If the agreed payment differs from the evidence, ask the adviser whether that creates a tax or legal consequence.
The home was changed or is not a normal home
Major works before death, a right of use, an occupied property, annual ground rent or a business premises can change the evidence needed. Describe the exception before the inspection.
Mistakes that create disputes or delay
- Treating the WOZ value as the market value for a family buyout.
- Choosing a valuation date after the report has already been ordered.
- Leaving out a mortgage, right of use, leasehold or major renovation.
- Asking the valuer to settle inheritance shares or tax questions.
- Comparing prices without comparing the report scope and recipient requirements.
- Editing the value in a family spreadsheet without preserving the report and its assumptions.
The informed objection is that a formal report may be unnecessary when the tax authority’s WOZ route answers the tax question. That is correct in some cases. The practical test is not “can a valuer produce a number?” but “will this evidence answer the actual decision and be accepted by the person receiving it?”
What to do after the valuation
Save the report with the documents that were supplied and record who received it. If the property remains in the estate, note the review date and any change in condition or use. Do not silently replace the original report when a later event changes the value; commission or request an update that states the new date and reason.
If heirs disagree, list the precise disagreement: a factual error, a missing right, the valuation date, the comparable evidence or the division calculation. A focused question is easier to review than a general statement that the number “looks wrong.”
Frequently asked questions
Do I always need a professional valuation for inheritance tax?
No. The tax authority provides a WOZ-based route for many inherited homes. A professional valuation may still be useful for a substantial change, a non-standard property, a family buyout, a sale or a separate financing requirement.
Which date should an inheritance valuation use?
That depends on the purpose. Inheritance-tax rules use specific WOZ years and exceptions. A sale, buyout or mortgage can require a different date. Confirm it before booking.
Can the heirs choose their own value?
They can discuss and agree a transfer price, but an agreed price is not the same as an independent market valuation. Ask a notary or tax adviser about any difference and its consequences.
Does the mortgage reduce the home’s value?
The mortgage is a debt that can affect the net estate. It is not the same as changing the property’s market value. Keep the property value and debt calculation as separate lines.
What if someone has a right to live in the home?
A right of use or usufruct can change who may occupy the property and how the interests are valued. Tell the valuer and ask the notary or adviser how the right affects the estate.
Heir’s valuation checklist
Before requesting a report, check:
- The purpose, recipient and valuation date are written down.
- Ownership, heirs, rights of use and mortgage information are available.
- The relevant WOZ notices and property documents are collected.
- Renovation, leasehold, occupancy and unusual features are disclosed.
- The report type, inspection and acceptance requirements are confirmed.
- The final report is checked before it is used for tax, division, sale or financing.
Beste Taxateur helps you organise the questions and evidence around property valuation for inheritance Netherlands, so you can compare providers and prepare the next step. The relevant lender, adviser, municipality or other party decides which report or evidence it accepts.
Ask a question about property valuation for inheritance Netherlands