What Documents Do You Need for a Property Valuation in the Netherlands?
Use this practical document checklist before a Dutch property valuation. Learn what is commonly useful, what depends on the purpose and how to protect private information.
TL;DR: documents needed for a property valuation
Start with the property address, basic property details, the reason for the valuation and the organisation that will receive the report. Then add documents that explain ownership, leasehold, the homeowners’ association, energy performance or renovation work when they apply to your home.
If you are assembling a valuation file, add local context such as property valuation in Woningtaxatie Erfpacht, Amsterdam only after recording the address, purpose and valuation date.
If you are buying an apartment, match apartment property valuation to the unit, VvE documents and lender requirements.
The NRVT residential report requirements include recurring property fields such as address data, photographs, the object description, maintenance, location, measurement sources, the use of the home and the valuation purpose.
There is no universal document bundle for every valuation. A mortgage lender may require a particular report and validation route, while a sale discussion or an inheritance matter may need a different evidence set. Send the same clear brief to each provider and ask which documents they need before the inspection.
Before you book an inspection, ask the lender which valuation report the lender accepts fits your application.
Why the document list changes by purpose
A valuation is an assignment with a defined purpose. A report for a mortgage answers a different question from a valuation for a sale conversation, refinancing, division of assets or a renovation plan. The purpose affects the report recipient, the information that matters and the checks that must be completed.
If your deadline is fixed, allow for property valuation timing before you book the inspection.
The NRVT’s residential practice guidance on dossier formation describes a professional file as more than a final PDF. It can include assignment terms, relevant correspondence, inspection data, source information, drafts, responses and the final report with required attachments. For a homeowner, that translates into a practical principle: give the valuer reliable context and keep a record of what you supplied.
The core information to prepare first
These details help a valuer understand the assignment and identify gaps early:
- the full property address and postcode;
- the type of home, ownership form and current use;
- the reason for the valuation;
- the intended report recipient, such as a lender or adviser;
- your preferred inspection and delivery timing;
- the names of the owner or commissioning party when requested through a secure channel;
- details of any recent purchase, sale, mortgage change or planned financing.
The NRVT model-report materials for 2026 show why property description, photographs, location, maintenance and valuation purpose recur in residential valuation work. The report itself still depends on the inspection and the valuer’s professional analysis.
Property and ownership documents
The following may be useful, depending on the home:
- Purchase or ownership information
- Purchase agreement, ownership details or other evidence that clarifies the property and the person commissioning the assignment.
- Leasehold
- Leasehold conditions, ground-rent details and dates when the lease changes, if the property is leasehold.
- Homeowners’ association
- Relevant VvE information, service charges, reserve-fund information or planned major works for an apartment.
- Plans and measurements
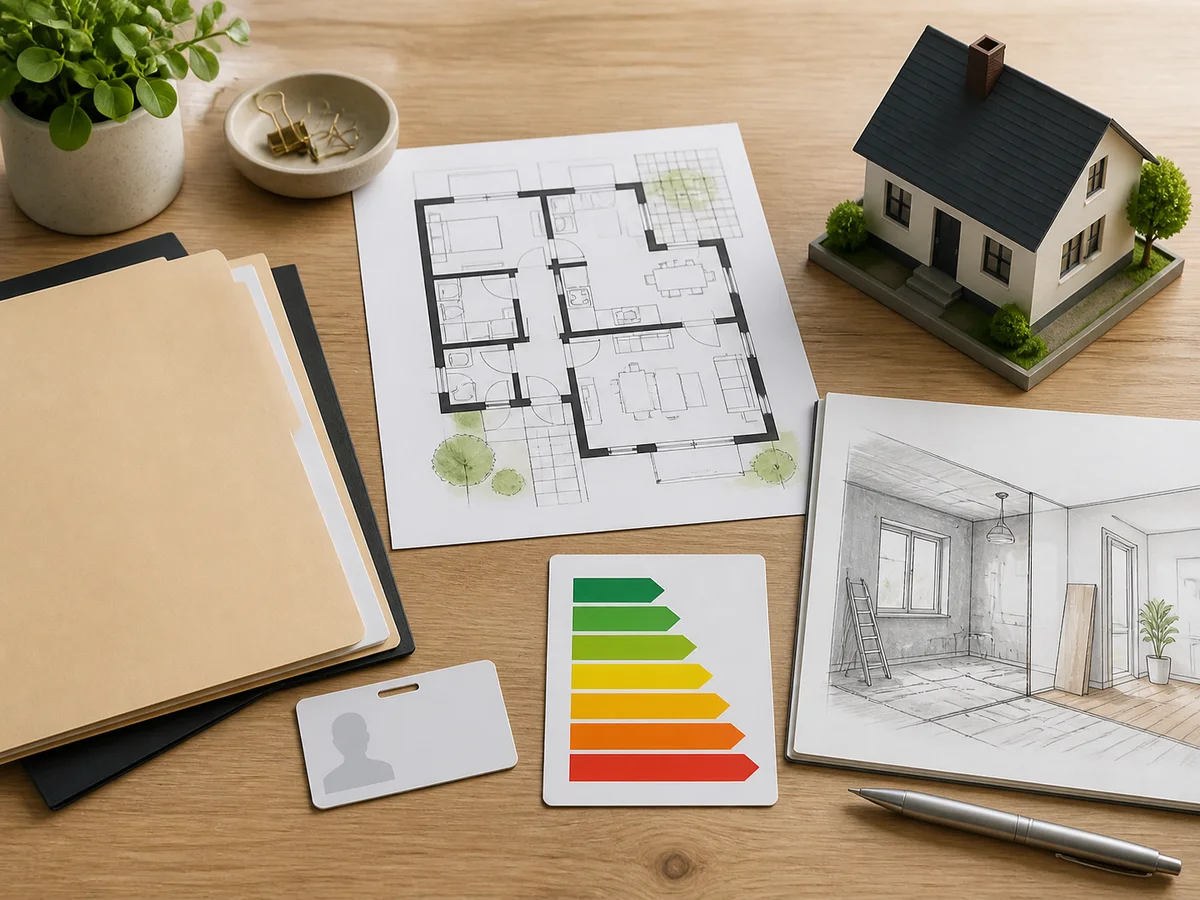
- Floor plans, extension drawings and reliable surface-area or layout information when available.
- Property condition
- Recent information about defects, repairs, maintenance or known restrictions that may affect the inspection or analysis.
Do not assume that every item is mandatory. A document is valuable when it answers a question about the property, the assignment or a relevant risk. Extra files that are unrelated, outdated or difficult to verify can slow the review without improving the report.
Renovation and improvement documents
Tell the valuer about completed, ongoing and planned work. Useful evidence can include:
- building permits or approvals where relevant;
- architectural drawings or floor plans showing the change;
- contractor quotes and invoices;
- a clear renovation budget or specification;
- photographs of the work before, during or after completion;
- warranties, completion documents or energy-improvement evidence;
- information about structural changes, extensions, insulation, heating or installations.
For a mortgage application, the lender may require a specific renovation budget or a particular form. ABN AMRO’s public valuation and mortgage-document guidance illustrates this lender-specific approach. Use it as an example of the kind of detail a mortgage process can request, then confirm the actual list with your own lender or adviser.
Apartment evidence deserves its own check
If the property is an apartment, collect the deed of division, current VvE information, service-charge details, meeting minutes and any MJOP before the assignment starts.
Energy, environment and location information
An energy label can help describe the property, especially when energy improvements are part of the story. Other relevant information may include known environmental issues, foundation information, flood or soil concerns, easements, rights of way and location-specific restrictions. Relevance depends on the home and the valuation purpose.
They also show that some topics, including energy or environmental matters, are conditional rather than a fixed requirement for every file.
Mortgage and report-recipient checks
Before collecting sensitive information, ask the recipient:
- Which report format does it accept?
- Is validation required?
- Which person or organisation must be able to rely on the report?
- Is a recent report available, and if so, how old may it be?
- Does the application involve renovation, refinancing, a loan increase or another special purpose?
A general checklist can prepare you for the conversation, while the lender’s current policy decides what works for the application.
Privacy: send the minimum necessary information
Property files often contain addresses, identity information, purchase prices, mortgage details and private correspondence. Use the provider’s secure upload or email process, check the recipient address and ask how the documents will be stored. Remove unrelated personal information where it is not needed for the assignment.
This is also a quality issue. A clean, labelled dossier makes it easier to distinguish current documents from old versions and helps the valuer trace important property facts without searching through unnecessary personal data.
A practical preparation order
Use this order when you want to keep the process efficient:
- Write down the valuation purpose and report recipient.
- Gather the address, property type, ownership form and any special conditions.
- Add plans, measurements, VvE, leasehold, energy and renovation evidence where relevant.
- Separate current documents from historic or superseded versions.
- Ask the valuer and lender which items are missing before the inspection.
- Send only the required documents through a trusted channel.
Preparing early gives the provider time to identify a missing plan, approval or report requirement before the appointment.
The informed caveat: a long dossier is not automatically a better dossier
More documents can provide more context, while a large unfiltered file can create uncertainty about which facts are current. The goal is a complete, relevant and traceable dossier. A valuer still needs to inspect the property, assess the evidence and apply the relevant professional standards.
If a provider asks for something that seems unusual, ask what decision it supports. If the request comes from a lender, ask whether the item is a lender rule or a valuer preference. That distinction helps you resolve gaps without treating every request as a universal requirement.
Frequently asked questions
Do I need a floor plan for every valuation?
No. A floor plan is useful when it clarifies layout, extensions or measurements, but the exact requirement depends on the property and assignment. Tell the provider what you have and ask whether a replacement measurement or inspection is needed.
Do I need my mortgage offer before ordering a valuation?
Not always. You do need to know the purpose and likely report recipient, because those details can affect the report route. Ask your adviser which evidence must be available at each stage.
What should I provide after a renovation?
Share evidence that explains the scope, cost, approval and completion status of the work. Drawings, permits, quotes, invoices and photographs can be relevant. The lender or valuer may request a specific format.
Can I send every document I have?
You can prepare a wider file, but send only relevant information through a trusted channel. Label current documents clearly and remove unrelated personal data where it is unnecessary.
Beste Taxateur helps you organise the questions and evidence around documents needed for property valuation, so you can compare providers and prepare the next step. The relevant lender, adviser, municipality or other party decides which report or evidence it accepts.
Ask a question about documents needed for property valuation