When Do You Need a Property Valuation in the Netherlands?
Use a purpose-first decision framework to determine when you need a formal property valuation, which value applies and who must accept the report.
TL;DR: start with the decision, not the report
You need a property valuation when a person, lender, insurer, court, tax adviser or another decision-maker needs a defensible opinion of value for a defined purpose and date. A formal report is not automatically necessary for every question. A lender may accept another route, while a buyer who wants a quick pricing conversation may only need an early indication.
If you are deciding whether to order a valuation, compare the decision-maker’s evidence requirement with local context such as property valuation in Taxatie Beleggingspand, Amsterdam rather than treating every estimate as equivalent.
Before you book an inspection, ask the lender which valuation report the lender accepts fits your application.
The Rijksoverheid explanation of WOZ valuation describes a municipal process with its own reference date and purpose.
Use four questions before you request a quote:
- What decision will the value support? A purchase, mortgage, sale, renovation, insurance, inheritance or dispute can require different evidence.
- Who must accept it? A lender, notary, insurer, court or family agreement can impose its own format and age requirements.
- Which value basis applies? Market value, value after works, reinstatement value and another basis are not interchangeable.
- What format is required? The recipient may want a full report, validation, a specific platform or another accepted product.
If you cannot answer these questions, pause before ordering. The cheapest report can be expensive when the recipient rejects it or when it answers the wrong question.
Before you rely on the result, compare the valuation report contents with the question the assignment had to answer.
Does this situation match your question?
If you are a homeowner, buyer, seller, heir, business owner or adviser who is unsure whether a formal property valuation is needed. It helps you decide what to ask the recipient and which documents to prepare.
If you are buying a home, match property valuation before buying to the mortgage question, valuation date and lender requirements.
It does not replace mortgage, legal, insurance or tax advice. Those decisions can involve rules beyond the value of a property. A valuation supplies a defined opinion of value; it does not approve a loan, set a tax bill or guarantee a sale.
Before you appoint a valuer, define the right type of property valuation by the purpose and report recipient.
Context: one word, valuation, covers different questions
People often use “valuation” for a formal report, an estate-agent estimate, an online calculator, a municipal WOZ value or an informal opinion. These products can be useful for different decisions. Treating them as substitutes creates avoidable confusion.
As you prepare for a valuation, gather documents needed for a property valuation before the inspection takes place.
That does not automatically make the WOZ value the correct evidence for a private purchase, lender or insurance decision.
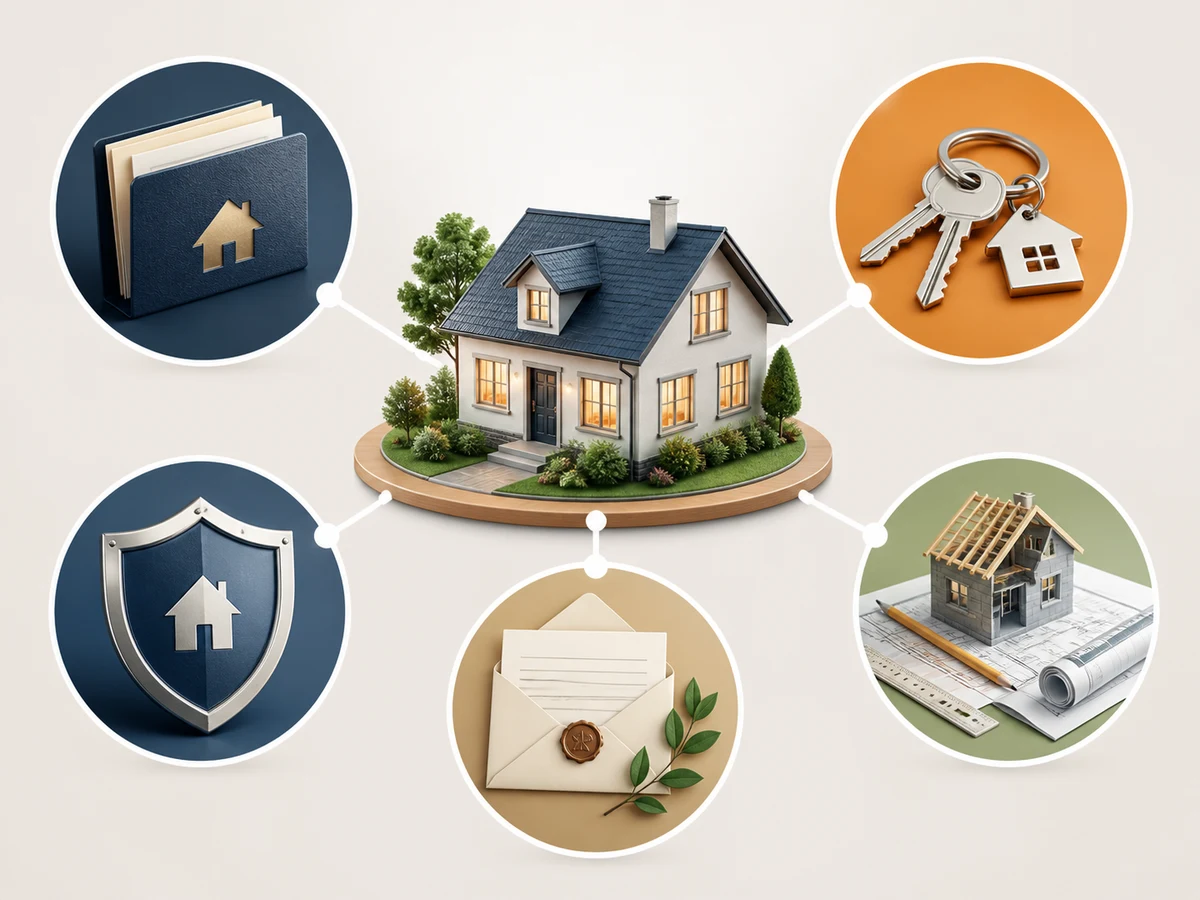
The body visual maps a single home to different decision paths. It is a reminder to choose the evidence after identifying the question, rather than a claim that one product is always required.
If your question concerns tax or WOZ, keep the tax rule and property valuation for a WOZ objection as separate parts of the assessment.
What to identify before ordering
- Purpose
- Write the decision in one sentence, such as “the lender must assess the current value for a refinance.”
- Recipient
- Name the organisation or person that will rely on the report and ask for its current acceptance rules.
- Date
- Confirm the required valuation date and how recent the inspection or report must be.
- Value basis
- Clarify market value, value after renovation, reinstatement value or another defined basis.
- Property facts
- Record address, ownership, leasehold, use, floor area, condition, improvements and planning information.
- Format
- Ask whether the recipient needs a full report, validation, a digital product or another specific format.
Constraints that determine the right evidence
The recipient controls acceptance
An independent report can still be unsuitable for a lender or insurer if the format, date, purpose or assumptions do not fit. Ask the receiving party first and keep the answer in writing.
The value basis controls the question
Market value asks what the property could reasonably exchange for under defined conditions. Reinstatement value concerns rebuilding for insurance. Value after renovation depends on the specified works and assumptions. These figures should not be mixed because their decisions differ.
The property can be legally or physically unusual
Leasehold, split ownership, a protected building, mixed use, an unregistered extension or a planning restriction can change the assignment. Tell the valuer early so the scope and evidence are clear.
Rules and policies can change
Mortgage, tax and insurance requirements are not permanent. Use current information from the recipient and relevant official guidance. An old checklist can be a useful starting point, not final confirmation.
The AFM mortgage guidance gives a practical example: a provider may ask for a valuation report, while another evidence route can sometimes be accepted.
The decision process in six steps
1. State the decision
Write what must be decided, by whom and by when. “I want to know what my home is worth” is a starting question. “My lender needs a current market value for a refinance” identifies an assignment.
2. Separate evidence from curiosity
Decide whether you need a report that another party will accept or only an indication for planning. This distinction prevents a casual estimate from being used in a formal application.
3. Confirm the value basis
Ask which value, reference date and assumptions fit the decision. Include planned works, vacant possession, rental status or another condition when it matters.
4. Confirm the format and deadline
Ask who orders the report, where it is delivered, whether validation is required and how long review takes. Include time for corrections rather than using the inspection date as the deadline.
5. Prepare the evidence
Gather deeds, plans, permits, leasehold terms, energy documents, renovation invoices, rental information and earlier reports that explain the property. Do not hide a defect or an unresolved legal issue because it could change the assignment.
6. Review the result against the question
Check the purpose, date, value basis, assumptions, factual description and recipient requirements.
Six common property decisions
Buying a home
A lender may need a mortgage valuation, while a buyer may also want condition or price advice.
Refinancing or increasing a loan
The lender may need current value evidence, but acceptance can differ by provider. Confirm the route before ordering a report and keep the affordability question separate.
Selling a home
An owner may need a market indication to set expectations, or a formal report for a separate lender or legal purpose. A valuation is not a guarantee of the achieved sale price.
Renovating
When extra borrowing depends on planned work, the recipient may ask for value after renovation and evidence of the project. A construction budget alone does not determine the added value.
Insuring
Insurance can focus on reinstatement or rebuilding rather than market value. Ask the insurer which figure and assumptions it requires.
Inheritance, gift or dispute
The relevant date, legal purpose and value basis may be specific. Tell the valuer and adviser what the report must support before the inspection.
Mistakes that lead to the wrong report
Starting with a generic quote
Why it happens: price is easy to compare. Fix: compare scope, recipient, date and format before comparing fees.
Assuming every valuation is interchangeable
Why it happens: the word “value” sounds universal. Fix: name the value basis and the decision in the brief.
Treating the WOZ value as a private report
Why it happens: it is an official figure that is easy to find. Fix: ask the receiving party whether it accepts the WOZ value for this purpose.
Leaving the recipient unnamed
Why it happens: the homeowner expects the report to speak for itself. Fix: state who will rely on it and confirm acceptance in advance.
Omitting changes to the property
Why it happens: the owner assumes the valuer can discover everything. Fix: provide permits, plans, invoices and a clear description of the works.
Aftercare: keep the purpose attached to the report
Save the final report with the request that defined its purpose, date and recipient. Record any assumptions that must remain true. If the decision is delayed or the property changes materially, ask whether the report is still usable.
When a lender or adviser asks for a correction, check whether the issue is factual, methodological or a new requirement. Keep the correspondence with the report so a later reviewer can understand what changed.
Frequently asked questions
Do I need a formal valuation to sell my home?
Not automatically. A seller may want a market indication for pricing, while a lender, court or another recipient may require a formal report for a separate decision.
Is an online value estimate a property valuation?
It can be a useful orientation, but it normally does not replace a report that a named recipient must accept. Check the purpose and format before relying on it.
Is a WOZ value enough for a mortgage?
Sometimes a provider may accept it, but that is lender- and application-specific. Ask the lender before treating it as a substitute.
Does every renovation require a new valuation?
No. It depends on the financing, purpose, size of the works and the recipient’s requirements. When value after renovation matters, ask which evidence is needed.
Can one report be used for several purposes?
Sometimes, if the assignment, value basis, date and recipients fit all decisions. Do not assume that a mortgage report also answers an insurance, tax or legal question.
Property valuation decision checklist
- The decision the value must support is written down.
- The report recipient and current acceptance rules are confirmed.
- Required valuation date and age limit are known.
- Value basis and material assumptions are identified.
- Property changes, legal rights and unusual facts are disclosed.
- Required report format, validation and delivery route are confirmed.
- Time for inspection, corrections and recipient review is included.
Beste Taxateur helps you organise the questions and evidence around when do you need a property valuation, so you can compare providers and prepare the next step. The relevant lender, adviser, municipality or other party decides which report or evidence it accepts.
Ask a question about when do you need a property valuation